

Table of Contents
- Which GST Registration Does Your Business Need?
- Who Needs GST Registration in India?
- Regular GST Registration
- GST Composition Scheme Registration
- Casual Taxable Person Registration
- Non-resident Taxable Person Registration
- Input Service Distributor (ISD) Registration
- SEZ Unit and SEZ Developer Registration
- GST TDS Registration
- GST TCS Registration for E-commerce Operators
- Voluntary GST Registration
- GST Registration Types: Quick Comparison for MSMEs
- How to Choose the Right GST Registration for Your MSME
- Conclusion
- FAQs
Introduction: Which GST registration does your business need?
The types of GST registration in India depend on your business activity, turnover, location, and the nature of your supplies. A manufacturer, trader, service provider, e-commerce operator, or government supplier may face different GST registration requirements. Choosing the right registration helps an MSME meet its tax obligations and avoid compliance issues.

This 2026 guide explains GST registration eligibility, the main registration types, key requirements, and important considerations for GST registration for MSMEs before you apply.
Who needs GST registration in India?
GST registration eligibility depends on aggregate turnover, the type of supply, the State or Union territory, and specific compulsory-registration provisions. Eligible suppliers of goods can generally have a ₹40 lakh threshold, while the general threshold for suppliers of services is ₹20 lakh. Lower thresholds apply in certain States and specified categories. Businesses should check the applicable rules before applying.
| Business situation | General threshold |
| Eligible suppliers of goods | ₹40 lakh |
| Suppliers of services | ₹20 lakh |
| Certain States and categories | Lower threshold may apply |
| Compulsory-registration cases | Registration may apply below the threshold |
Aggregate turnover: GST law calculates aggregate turnover on an all-India basis for the same PAN. It includes taxable supplies, exempt supplies, exports, and inter-State supplies, subject to statutory exclusions.
Compulsory registration: Certain persons must register even when turnover is below the applicable threshold. Section 24 covers specified categories, including casual taxable persons, non-resident taxable persons, certain inter-State suppliers, and other specified persons.
E-commerce supplies: Registration requirements for e-commerce operators and suppliers using online platforms depend on the applicable GST provisions and exemptions. An MSME should not assume that every e-commerce seller must register regardless of turnover.
Types of GST registration in India
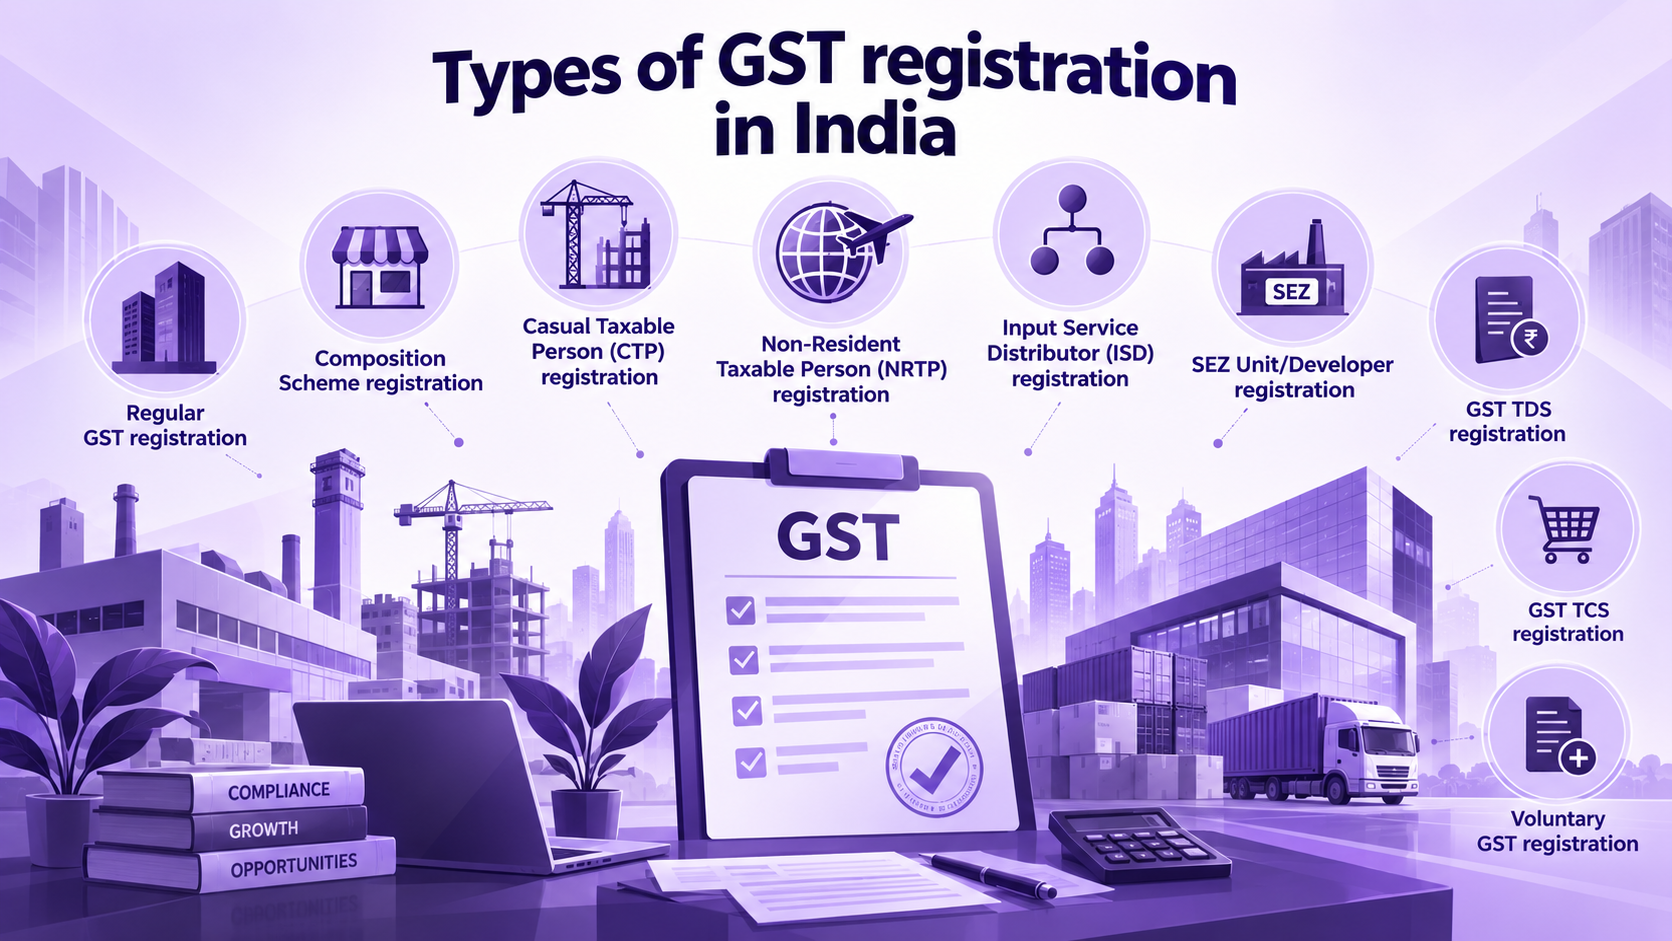
GST registration can apply in different ways depending on the taxpayer’s business model and statutory obligations. For MSMEs, the most relevant categories include regular registration and the Composition Scheme, while specialised registration provisions cover casual taxable persons, non-resident taxable persons, Input Service Distributors, TDS deductors, and TCS collectors. SEZ units and developers also have separate registration requirements.
Regular GST registration
A regular taxpayer operates under the normal GST framework and can be required to register when the applicable registration conditions are met. A person can also register voluntarily even when registration is not otherwise mandatory. Once registered, the taxpayer receives a GSTIN and must follow the applicable GST requirements.
For an MSME, regular registration can be particularly relevant when it:
- Supplies goods or services to GST-registered customers
- Needs to claim eligible Input Tax Credit (ITC)
- Falls under a compulsory-registration provision
- Plans to expand its taxable business across States
- Supplies to larger companies that require GST-compliant invoices
| Key feature | Regular GST registration |
| GSTIN | Issued after registration |
| Tax invoices | Can be issued for taxable supplies |
| ITC | Eligible ITC can be claimed, subject to GST rules. |
| GST returns | Applicable returns must be filed |
| Tax payment | GST must be paid as applicable |
A regular registration does not have a fixed expiry simply because it is a normal registration. Businesses must, however, keep their registration details updated and meet their ongoing GST compliance requirements. The GST Portal also confirms that a person registering voluntarily can select the normal taxpayer route.
GST Composition Scheme Registration
What is the GST Composition Scheme?
The GST Composition Scheme is a simplified tax framework for eligible small taxpayers. Instead of paying GST at the normal applicable rates, eligible businesses pay tax at prescribed composition rates and follow simpler compliance requirements. The scheme can help eligible MSMEs manage GST compliance with fewer reporting requirements. However, it also comes with important restrictions.
Who can opt for composition?
For eligible suppliers of goods, the general turnover limit is ₹1.5 crore in the preceding financial year. The limit is ₹75 lakh in the specified States listed under the applicable rules. A separate composition framework covers eligible suppliers of services or mixed supplies with turnover up to ₹50 lakh in the preceding financial year.
The scheme does not cover every business. Eligibility also depends on the nature of the business and the conditions under the CGST Act and Rules.
Key restrictions
A composition taxpayer:
- Cannot claim Input Tax Credit (ITC) on purchases
- Cannot collect GST separately from customers
- Must issue a bill of supply instead of a tax invoice
- Generally cannot make inter-State outward supplies
- Must meet the prescribed conditions for continuing under the scheme
| Regular GST | Composition Scheme |
| Normal GST rates apply | Prescribed composition rates apply |
| Eligible ITC can be claimed | ITC cannot be claimed |
| Tax invoice issued | Bill of supply issued |
| Broader eligibility | Specific eligibility conditions apply |
| Regular GST compliance | Simplified compliance framework |
For MSMEs: A manufacturer, trader, or eligible service provider should check turnover, business activity, customer requirements, and supply locations before choosing the composition route. The GST Portal also validates turnover when an applicant selects the composition option during registration
Casual Taxable Person Registration
A Casual Taxable Person (CTP) is someone who occasionally makes taxable supplies in a State or Union territory where they do not have a fixed place of business.
Who may need it: An MSME attending a trade fair, industry exhibition, or temporary sales event in another state may need CTP registration, depending on the applicable GST provisions.
Temporary nature: CTP registration is designed for businesses making taxable supplies on a temporary basis outside their usual place of business.
Advance tax: The applicant must generally make an advance deposit of the estimated GST liability for the period for which registration is sought.
Validity: Registration is generally valid for the period specified in the application or 90 days from the effective date of registration, whichever is earlier.
Extension: The validity period can be extended by up to 90 additional days, subject to the applicable provisions.
Application: A casual taxable person must apply for registration before starting taxable business activities in the relevant state or union territory.
Non-resident Taxable Person Registration
A Non-Resident Taxable Person (NRTP) is a person who occasionally undertakes taxable supplies in India but has no fixed place of business or residence in India.
Who may need it: This registration can apply to an overseas business supplying taxable goods or services in India on a temporary basis.
Temporary registration: NRTP registration covers the period for which the non-resident undertakes taxable activities in India.
Advance tax: The applicant must generally deposit the estimated GST liability in advance for the registration period.
Application: An NRTP must apply electronically before starting taxable business activities in India.
Documents: The application requires prescribed documents, including a valid passport. Additional documents apply to foreign companies and other entities.
Authorised signatory: The applicant must appoint an authorised signatory who is resident in India and can undertake the required GST compliance.
| CTP | NRTP |
| Person making temporary taxable supplies in a State/UT without a fixed place of business there | Non-resident person making taxable supplies in India |
| Temporary registration | Temporary registration |
| Advance tax requirement | Advance tax requirement |
Input Service Distributor (ISD) Registration
An Input Service Distributor (ISD) is a separate GST registration used by an office to receive invoices for eligible input services and distribute the related input tax credit to other GST registrations of the same organisation having the same PAN.
Who needs it: ISD registration is relevant to businesses that receive common input services, such as advertising, professional, or consultancy services, for use across multiple GST-registered locations.
Separate registration: An ISD must obtain a separate GST registration. The GST Portal provides ISD as a specific registration category under the registration application.
2025 update: Changes to the ISD provisions took effect from 1 April 2025, including changes covering certain inter-State reverse-charge transactions. Businesses using the ISD mechanism should follow the updated provisions.
ITC distribution: The ISD distributes eligible input service credit to the appropriate recipient registrations according to the prescribed rules.
GSTR-6: An ISD must file GSTR-6 to report the distribution of input tax credit.
MSME relevance: This registration becomes particularly relevant for multi-location MSMEs, manufacturing groups, and businesses with multiple GSTINs that centralise common services such as advertising, consulting, or professional services.
SEZ Unit and SEZ Developer Registration
An SEZ unit or SEZ developer must obtain a separate GST registration from its other business operations outside the SEZ. The GST Portal provides specific registration options for both SEZ units and SEZ developers. Supplies to an SEZ unit or developer can qualify as zero-rated supplies, subject to the conditions under GST law.
| Aspect | SEZ Unit | SEZ Developer |
| GST registration | Separate registration required | Separate registration required |
| Registration category | SEZ Unit | SEZ Developer |
| Purpose | Covers taxable activities of the SEZ unit | Covers taxable activities of the SEZ developer |
| Other business locations | Requires a separate GSTIN from non-SEZ locations | Requires a separate GSTIN from other business locations |
| Supplies received | Supplies from eligible suppliers can qualify as zero-rated | Supplies from eligible suppliers can qualify as zero-rated |
| MSME relevance | Useful for MSMEs operating from an SEZ | Relevant to businesses developing and operating SEZs |
Important: Zero-rating does not mean that every supply involving an SEZ automatically becomes tax-free. The supply must meet the applicable conditions under the IGST Act.
GST TDS Registration
GST TDS applies to government departments and other entities notified under Section 51 of the CGST Act that are required to deduct tax from specified payments to suppliers.
Separate registration: A person required to deduct GST TDS must obtain a separate GST registration for this purpose.
Registration form: Eligible tax deductors apply using FORM GST REG-07 under the GST registration rules.
TDS return: Registered deductors report deducted tax through GSTR-7 within the prescribed timeline.
MSME point: An ordinary MSME does not need GST TDS registration simply because it purchases goods or services. The requirement applies when the business or entity falls within the specified categories of persons required to deduct tax under Section 51.
GST TCS Registration for E-commerce operators
Tax Collected at Source (TCS) applies to an electronic commerce operator when the operator is required to collect tax under the GST law on supplies made through its platform.
Who needs it: The requirement applies to the e-commerce operator, not automatically to every seller using an online marketplace.
Separate registration: An operator required to collect TCS must obtain GST registration for its applicable obligations under the GST law.
TCS reporting: The operator reports the required TCS details through GSTR-8 within the prescribed timeline.
MSME point: An MSME selling through an e-commerce platform should not assume that the operator’s TCS registration automatically determines the seller’s own GST registration requirement. The seller must separately assess its GST registration eligibility and applicable exemptions.
Voluntary GST Registration
Voluntary GST registration allows a business that is not otherwise liable to register under the GST law to obtain registration. It is a registration route, rather than a separate taxpayer category such as a casual taxable person or non-resident taxable person.
Normal taxpayer status: A person registering voluntarily is treated as a normal taxable person and must follow the applicable GST requirements. The GST Portal provides “Voluntary Basis” as a reason for obtaining registration.
Why an MSME may consider it
| Consideration | How voluntary registration may help |
| B2B customers | Enables GST-compliant tax invoices |
| Input tax credit | Eligible ITC can be claimed subject to GST conditions |
| Business expansion | Provides a GSTIN for taxable business operations |
| B2B transactions | Can support transactions with GST-registered customers |
Important: Voluntary registration also creates GST compliance obligations. An MSME should therefore consider the compliance requirements before applying, rather than treating registration simply as a business credential.
GST Registration types: Quick comparison for MSMEs
The right GST registration type depends on the business model, statutory requirement, and nature of taxable activities. Use this table as a quick reference before checking the detailed eligibility rules for your business.
| GST registration type | Typically relevant to | Key feature |
| Regular taxpayer | Most taxable businesses | Normal GST framework with applicable ITC |
| Composition taxpayer | Eligible small businesses | Simplified tax and compliance framework |
| Casual taxable person | Temporary taxable activities in another State/UT | Temporary registration |
| Non-resident taxable person | Foreign businesses making taxable supplies in India | Temporary registration |
| Input Service Distributor (ISD) | Businesses distributing eligible input service credit | Separate ISD registration |
| SEZ unit/developer | Businesses operating as SEZ units or developers | Separate GST registration |
| TDS deductor | Government departments and other notified entities | GST TDS registration |
| TCS collector | E-commerce operators covered by TCS provisions | GST TCS registration |
| Voluntary registration | Persons not otherwise liable to register | Optional registration route |
Note: These categories do not all represent separate tax schemes. Some describe taxpayer status, while others apply to specific GST functions or business arrangements.
How to choose the right GST registration for your MSME
Use this quick checklist before applying for GST registration:
- What do you sell – goods, services or both?
- What is your aggregate turnover?
- Where do you make taxable outward supplies?
- Does any compulsory-registration provision apply to you?
- Do you need a special registration such as ISD, TDS, or TCS?
Manufacturer: Check turnover, supply locations, and applicable registration provisions.
Steel trader: Check turnover, customer requirements, and where you make taxable supplies.
Service MSME: Check the applicable threshold and nature of services.
Multi-State business: Check registration requirements for each State or Union territory where you make taxable outward supplies.
Conclusion
Choosing the appropriate GST registration in India starts with understanding how your business operates, where it makes supplies, and which GST provisions apply. For MSMEs, getting this right can affect invoicing, tax collection, input tax credit, and ongoing compliance. GST rules and notifications can change, so businesses should verify the latest requirements before applying or changing their registration. Check the GST Portal and CBIC for the latest 2026 requirements and applicable notifications.
Empowering MSMEs to grow smarter
Tata nexarc delivers powerful solutions for MSMEs—discover tenders, logistics solutions, and streamline procurement. Everything your business needs, all in one place.
FAQs
What are the types of GST registration in India?
Which GST registration is suitable for an MSME?
What is the GST registration turnover limit in India?
What is the difference between regular GST and composition GST?
What is casual taxable person GST registration?
Does a foreign business need GST registration in India?
What is ISD registration under GST?
How do you apply for GST registration online?
What documents are required for GST registration?
How long does GST registration take?
A product manager with a writer's heart, Anirban leverages his 6 years of experience to empower MSMEs in the business and technology sectors. His time at Tata nexarc honed his skills in crafting informative content tailored to MSME needs. Whether wielding words for business or developing innovative products for both Tata Nexarc and MSMEs, his passion for clear communication and a deep understanding of their challenges shine through.
90% business registered as normal GST payer and some choose as registration under composition scheme. What is other benefits of it?
no business owner is aware about such options. Even GST accountant or consultant will not advise around these options.
Data indicates that businesses under the Composition Scheme see a 30% reduction in compliance costs, although they lose out on ITC benefits. It’s a valuable trade-off for small enterprises.