
Table of Contents
- Introduction
- Understanding Voluntary Payment Under Section 74
- Procedure for Voluntary Payment Using Form GST DRC 03
- Voluntary Payment Before a Show Cause Notice: Penalty Benefits
- Tax Liability Under Section 74
- Penalties and Interest Under Section 74
- Show Cause Notice (SCN) Under Section 74
- Consequences of Skipping Payment Under Section 74
- Common Defences Against a Section 74 Show Cause Notice
- Section 73 vs Section 74 vs Section 74A — Spot the Difference Cheat Sheet
- Conclusion
The Goods and Services Tax (GST) revolutionised India’s taxation system in 2017. It aimed to simplify and unify the country’s complex tax structure. Within this framework, Section 74 of the Central Goods and Services Tax (CGST) Act, 2017 plays a crucial role in addressing cases of tax evasion involving fraud, wilful misstatement, or suppression of facts.

Section 74 of the Central Goods and Services Tax (CGST) Act gives businesses that have short-paid or wrongly claimed GST due to fraud, wilful misstatement, or suppression of facts a legal route to settle their tax liability through voluntary payment. File Form GST DRC-03 and pay the tax, interest, and applicable penalty. If payment is made before the Show Cause Notice (SCN) is issued, the penalty is generally 15% of the tax due, subject to the conditions under Section 74.
India’s GST regime, rolled out in 2017 to replace a maze of indirect levies, still trips up many MSMEs through data mismatches, misclassifications, or simple clerical errors. When officials believe the lapse is deliberate, Section 74 may apply. The language is tough, but the law also offers a practical route to resolve eligible liabilities through voluntary payment, reduce the applicable penalty, and potentially avoid prolonged tax disputes.
This guide explains the voluntary‑payment windows, the sliding penalty slabs, and the step‑by‑step process for filing DRC‑03 on the GST portal, so you can act before the meter starts running.
Understanding voluntary payment under Section 74
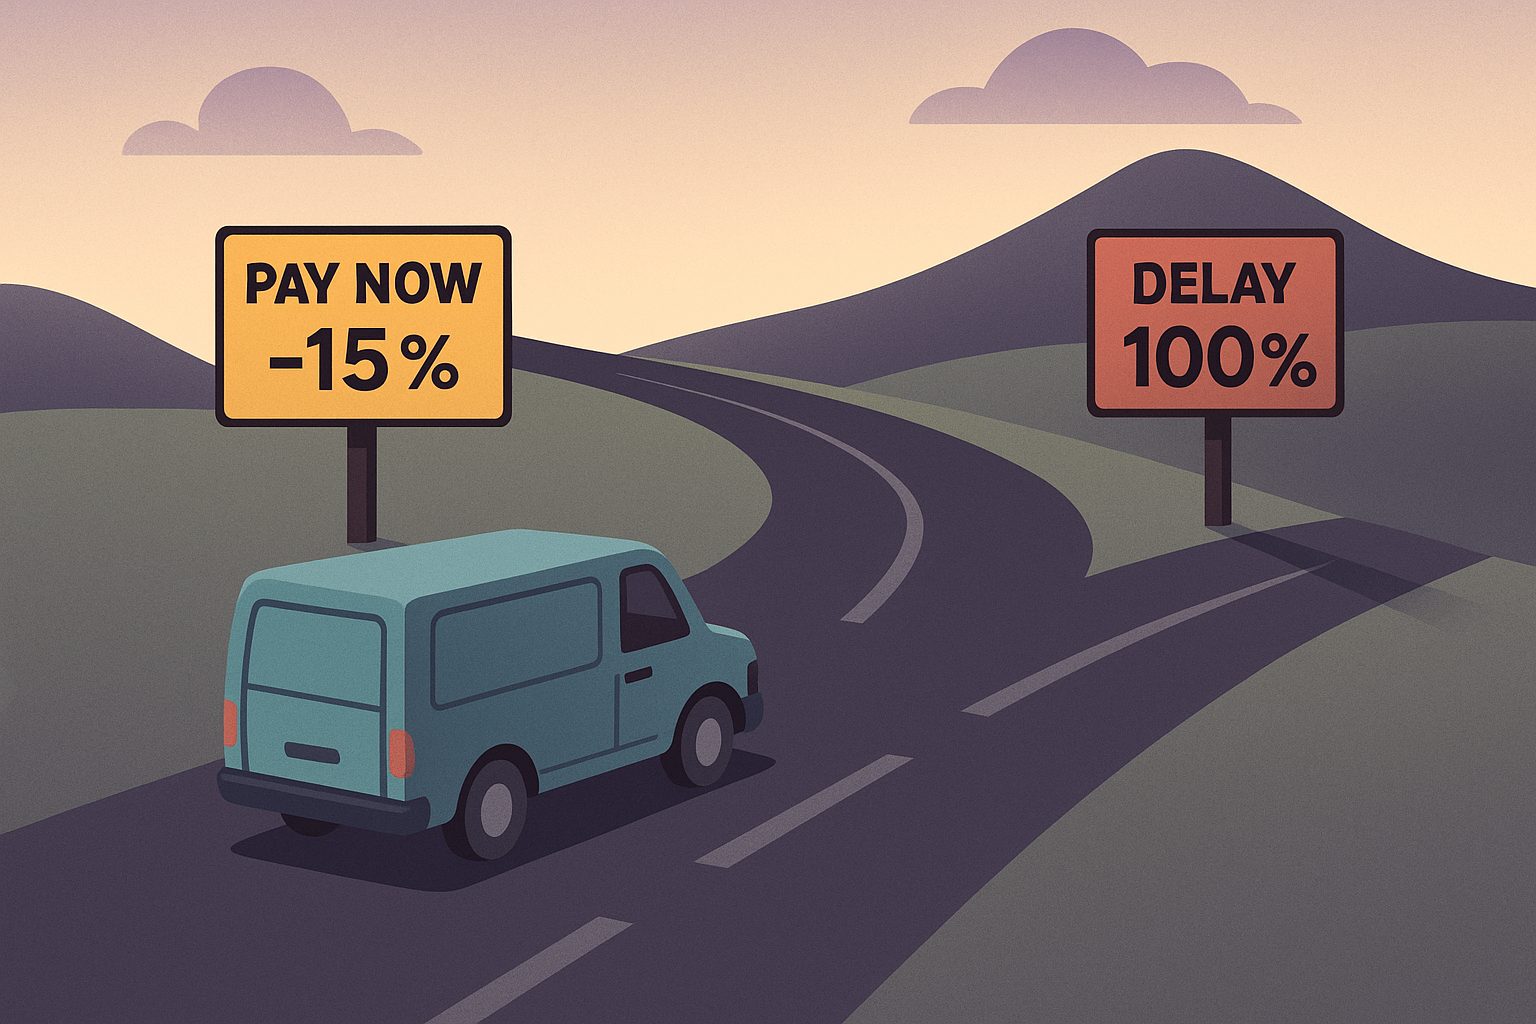
Voluntary payment under Section 74 lets a taxpayer clear the short-paid tax, interest, and a reduced penalty by filing Form GST DRC-03 either before a Show Cause Notice (SCN) is served or within 30 days of the notice being issued. Acting within this window can help conclude the proceedings for the amount paid, subject to the conditions prescribed under the law.
Why it’s worth moving fast
- Penalty capped:
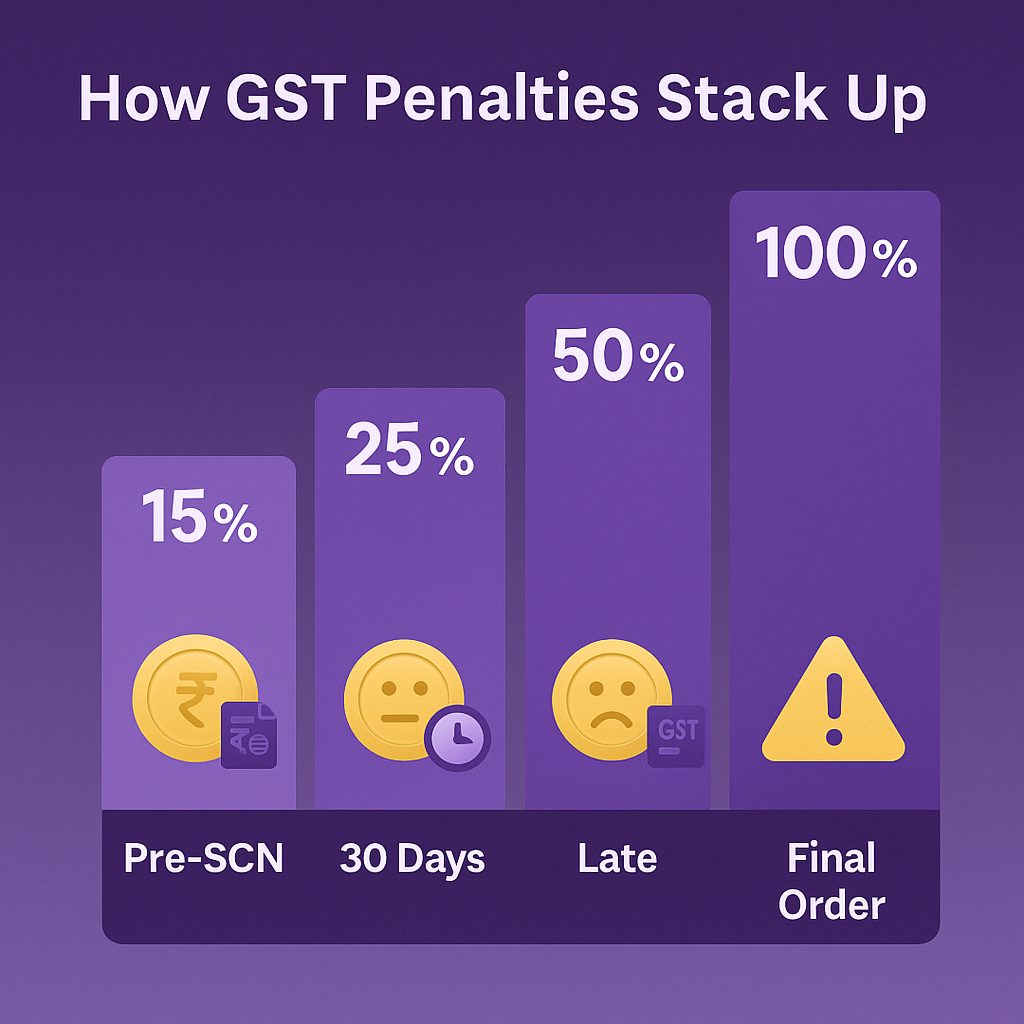
- Before an SCN – penalty is limited to 15 % of the tax amount.
- Within 30 days after an SCN – penalty rises to 25% of the tax amount.
-
After an order – the penalty can be reduced to 50% of the tax amount if the taxpayer pays within 30 days of communication of the order. Missing these payment windows can result in a penalty equivalent to 100% of the tax due under Section 74.
- Fewer legal headaches: Early compliance can help conclude proceedings relating to the tax paid and reduce the risk of prolonged disputes. However, it does not automatically prevent separate proceedings, including those under Section 132 of the CGST Act, where applicable.
- Room for re‑classification: Where the allegation of fraud is disputed, taxpayers may challenge the applicability of Section 74 and argue that the case should instead be treated as a non-fraud case under Section 73, where legally justified. Rule 142(1A) concerns the communication of ascertained tax, interest, and penalty before a notice; it does not, by itself, provide for reclassification or guarantee zero penalty.
Quick example
A wholesale trader discovers a ₹1 lakh GST short‑payment tied to mis‑classification. By filing DRC‑03 and paying tax plus interest before any SCN, the firm limits its penalty exposure to ₹15,000 and closes the matter – no prolonged correspondence, no courtroom stress. Delay beyond 30 days could have lifted that penalty to ₹25,000 or more.
Procedure for voluntary payment using form GST DRC-03
To settle dues under Section 74, you must file Form GST DRC-03 on the GST portal. The form works for both pre-SCN and post-SCN payments and records the tax, interest, and any applicable penalty. For tax periods from FY 2024–25 onwards, check whether Section 74A applies instead.
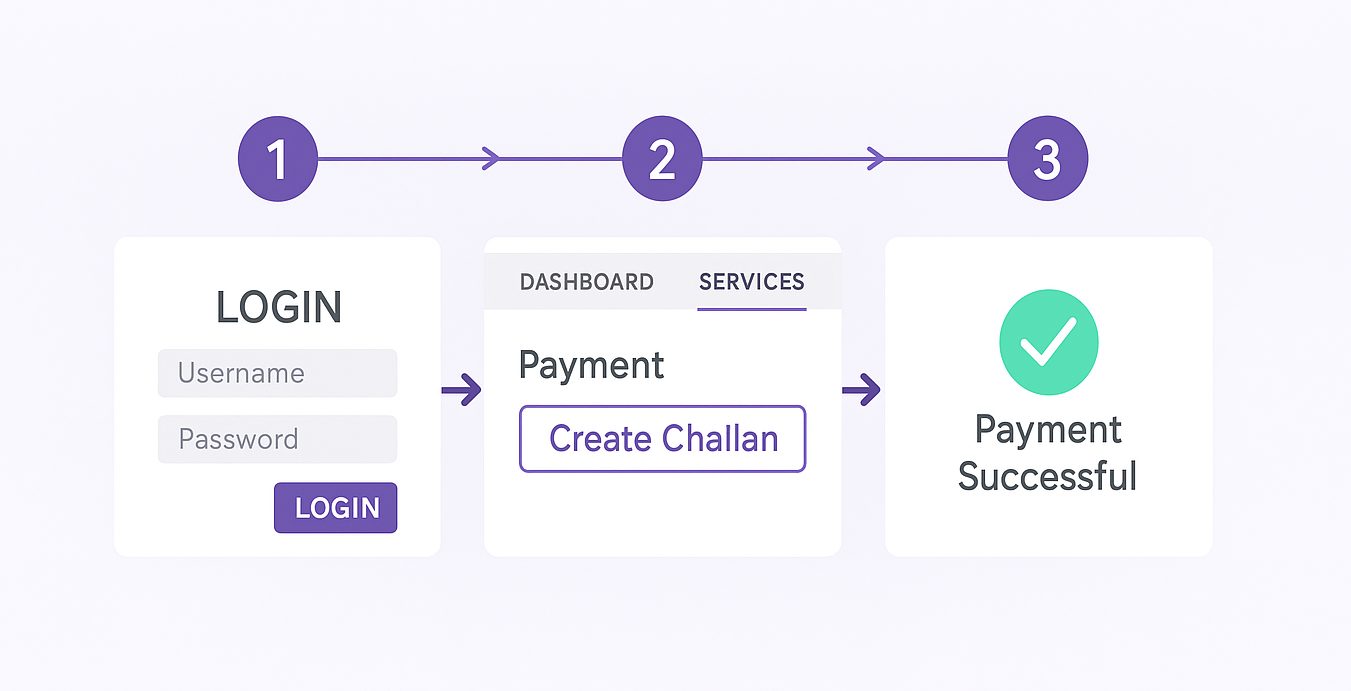
Step‑by‑step on the portal
- Log in at www.gst.gov.in with your GSTIN credentials.
- Go to Services ▸ User Services ▸ My Applications.
- Under Application Type, select Intimation of Voluntary Payment – DRC-03, then click New Application.
- Select the relevant cause of payment and enter the details required for the applicable tax period and proceedings.
- Enter:
- Tax amount (short‑paid or unpaid)
- Interest – generally 18% per annum for delayed payment of tax, where applicable. The rate and calculation depend on the nature of the liability and the relevant provisions of the CGST Act.
- Penalty – for eligible payments under Section 74, generally 15% of the tax if paid before the SCN, 25% if paid within 30 days of the SCN, or 50% if paid within 30 days of communication of the order. Different timelines apply under Section 74A.
-
If you are responding to an SCN, enter the relevant notice details and reference number wherever requested in the form.
-
Make the payment using the applicable electronic cash or credit ledger, as permitted by GST rules. If a challan is required, create it through the portal’s payment facility. Complete the payment and submit the DRC-03 application using the prescribed verification method
-
Download the filed Form GST DRC-03 acknowledgement and note the Application Reference Number (ARN). Keep these records with your working papers for future reconciliation or departmental verification.
Important: The exact portal fields and payment options may vary depending on the reason for payment and the stage of proceedings. Always verify the applicable tax, interest, penalty, and payment deadline before filing.
Pro‑tip: The GST portal may retain an unsubmitted Form GST DRC-03 draft for a limited period. Verify the current draft-retention period on the portal before relying on it, and save a copy of the details for internal approvals and records.
You must file DRC-03 before an SCN is issued or within 30 days of the SCN for eligible payments under Section 74 to qualify for the applicable reduced-penalty benefit. For fraud-related cases under Section 74A, applicable to FY 2024–25 onwards, the corresponding payment window is generally 60 days. Always verify the relevant provision and deadline before making payment.
For a visual walk‑through, the GSTN’s screenshot guide is handy:
https://tutorial.gst.gov.in/userguide/demandsandrecovery/Manual_GST_FORM_DRC-03.htm
Voluntary payment before SCN: Penalty benefits
Paying up before the tax officer serves a Show Cause Notice is the cheapest off‑ramp you will ever get under Section 74.
| Timing of payment | What you settle | Penalty charged | Why it matters |
|---|---|---|---|
| Before SCN is issued | Tax + interest | 15% of the tax | Lowest slab; a notice will not be issued for the tax paid, subject to statutory conditions. |
| Within 30 days after SCN | Tax + interest | 25% of the tax | Still a bargain, but you’ve lost 10 points. |
| After SCN, before order | Tax + interest | Generally, 100% of the tax if the matter proceeds to an order. | The 50% reduced penalty applies if you pay the tax, interest, and penalty within 30 days of communication of the order. |
| After final order | Tax + interest | 100% of the tax, unless the reduced-penalty conditions are met. | Prosecution may also be initiated where the legal requirements are satisfied. |
Example
A distributor uncovers a ₹1 lakh GST short-payment tied to forged purchase invoices. If the firm pays before any SCN, the penalty is ₹15,000, subject to the applicable conditions. Wait until the officer issues an SCN and those same dues will cost ₹25,000 if payment is made within 30 days of the notice. If the matter proceeds to an order, the penalty can be ₹1 lakh. However, paying the tax, interest, and 50% penalty (₹50,000) within 30 days of communication of the order can conclude the proceedings relating to that tax demand.
Early payment can help resolve the tax liability before a formal notice is issued for the amount paid. However, do not assume it automatically prevents prosecution or guarantees that the matter will remain absent from every public record or analytics system.
2026 update
Section 74 applies to relevant tax periods up to FY 2023–24. For FY 2024–25 onwards, Section 74A applies. In fraud-related cases under Section 74A, the reduced-penalty payment windows are generally 60 days after the notice or 60 days after communication of the order.
Tax liability under section 74
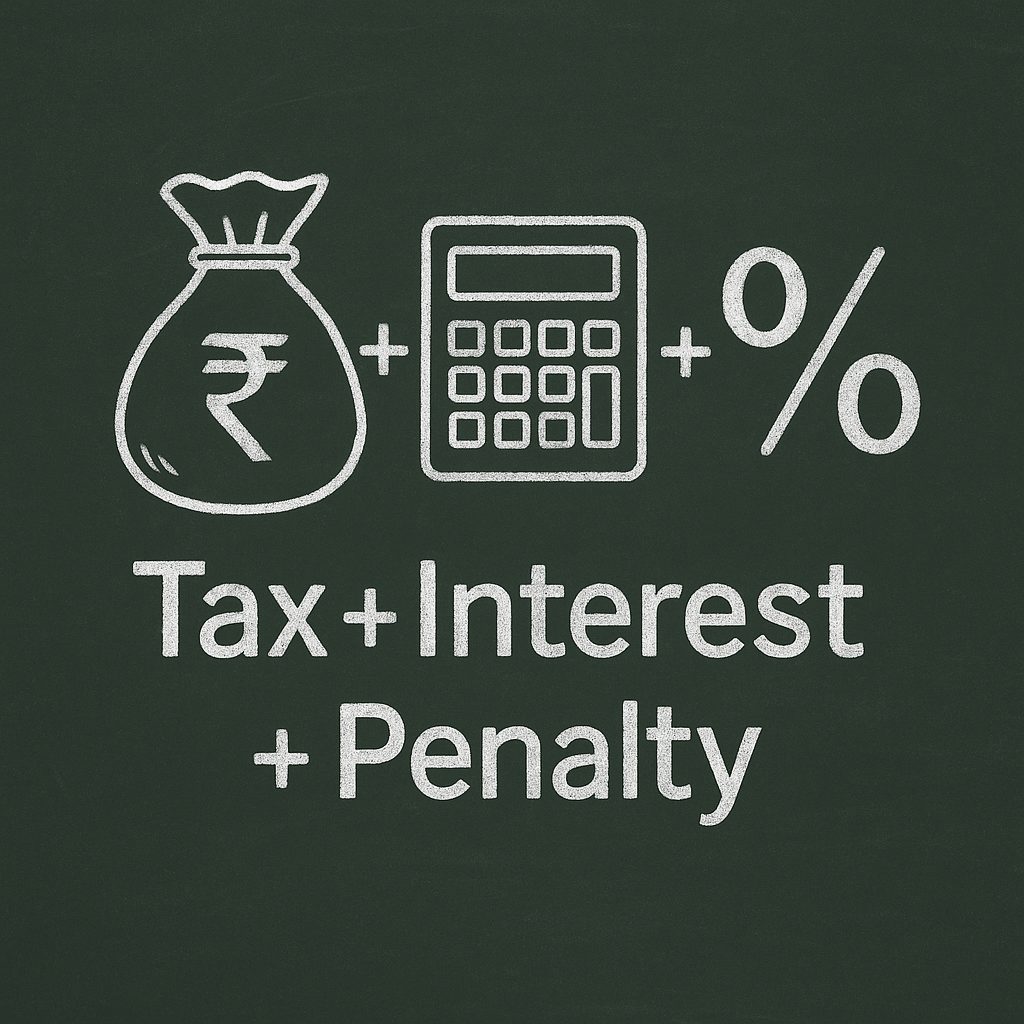
When you opt for voluntary payment, you must clear three components (tax, interest, and the applicable reduced penalty) to qualify for the relevant benefit. The GST portal records these payments through Form GST DRC-03, but it helps to break the calculation down yourself first.
Formula
Total liability = Unpaid/short‑paid tax
+ interest (generally 18% p.a. under Section 50(1), calculated from the day after the original tax due date until payment, subject to applicable rules)
+ penalty (15% if paid before the SCN, or 25% if paid within 30 days of the SCN, under Section 74)
Worked example
Suppose a trader failed to report taxable outward supplies worth ₹1 lakh for exactly one year:
| Component | Amount | How it’s derived |
| Short‑paid tax | ₹1,00,000 | Your undisclosed liability |
| Interest @18 % | ₹18,000 | ₹1,00,000 × 18 % × 1 year |
| Penalty (before SCN, 15 %) | ₹15,000 | ₹1,00,000 × 15 % |
| Total to pay | ₹1,33,000 | Sum of all three |
If the taxpayer instead pays within 30 days of the SCN, the penalty increases to ₹25,000, taking the total to ₹1,43,000, assuming the same tax and interest amounts. This illustrates why timely voluntary payment matters.
Heads-up: Interest is simple, not compound, and the applicable liability must be calculated using the relevant statutory provisions. If a taxpayer disputes the application of Section 74 and seeks treatment under Section 73, the tax and applicable interest do not automatically disappear. Always check the portal’s calculation against your records and payment dates, and resolve discrepancies before filing.
Penalties and interest under Section 74
Section 74 uses a stage-based penalty structure to encourage taxpayers to settle eligible liabilities early. The applicable penalty rates are:
- 15 % of the tax – if you pay before any Show Cause Notice is issued.
- 25 % – if you settle within 30 days after receiving the SCN.
- 50 % – if you pay the tax, interest, and penalty within 30 days of communication of the adjudication order.
- 100 % – the standard penalty under Section 74 if the matter proceeds to an order and the reduced-penalty conditions are not met
Interest on delayed tax payment is generally 18% p.a. under Section 50(1) and is calculated for the applicable period of delay. Wrongly availed and utilised input tax credit may be subject to a different interest provision under Section 50(3). Interest is generally calculated on a simple basis, using the applicable statutory method and dates.
2026 update: Section 74 applies to relevant tax periods up to FY 2023–24. For FY 2024–25 onwards, Section 74A applies, with different timelines for qualifying reduced-penalty payments. Verify the applicable provision before calculating your final liability.
Quick illustration
A taxpayer evades ₹1,00,000 in GST:
| When liability is cleared | Penalty | Total cash outflow* |
|---|---|---|
| Before SCN | ₹15,000 | ₹1,15,000 + interest |
| Within 30 days of SCN | ₹25,000 | ₹1,25,000 + interest |
| Within 30 days of communication of the order | ₹50,000 | ₹1,50,000 + interest |
| After the order, without qualifying for the reduced penalty | ₹1,00,000 | ₹2,00,000 + interest |
*Interest (generally 18% p.a. under Section 50(1), where applicable) is added to each scenario based on the period of delay and the applicable statutory calculation. The actual amount payable depends on the relevant dates and circumstances.
The maths alone tells the story: act promptly, reduce the applicable penalty where the law permits, and resolve the tax liability before the dispute escalates.
2026 update: These penalty stages apply to eligible cases under Section 74 for relevant tax periods up to FY 2023–24. For FY 2024–25 onwards, check Section 74A, which provides different payment windows.
Show Cause Notice (SCN) under Section 74
An SCN is the department’s formal way of saying, “We believe you’ve underpaid GST due to fraud, wilful misstatement, or suppression of facts – explain your position or pay the amount due.” The notice typically contains four elements:
- Alleged under‑payment – the amount and the tax heads (CGST/SGST/IGST).
- Grounds – why the officer believes fraud, wilful misstatement, or suppression of facts exists.
- Proposed penalty and interest – the amounts proposed under the applicable provisions, including any penalty for fraud-related cases.
- Response window – the deadline specified in the notice, generally allowing at least 30 days to respond, subject to the applicable law and circumstances.
Your options once an SCN lands
| Path | What you do | Cost profile | Practical notes |
|---|---|---|---|
| Settle within 30 days | File DRC-03, pay tax + interest + 25% penalty | Second-lowest slab | For eligible Section 74 cases, paying within 30 days of issue of the SCN concludes proceedings relating to that notice, subject to statutory conditions. |
| Contest | File a written reply, attach evidence, seek personal hearing. | The final liability depends on the outcome; a 100% penalty may apply if the demand is confirmed and reduced-penalty conditions are not met. | Be ready with reconciliations, invoices, and evidence addressing the allegations of fraud or suppression. |
| Do nothing | Ignore the notice | The department may decide the case based on available records, confirm the demand, and initiate recovery proceedings. | Depending on the circumstances and statutory requirements, further consequences may include recovery action, provisional attachment, registration-related action, or prosecution. |
Tick‑tock: The deadline to respond starts according to the notice and applicable service rules. The separate 30-day reduced-penalty window under Section 74 runs from the date the SCN is issued. Ask for an extension only if you genuinely need more time and can explain why; an extension is not automatic.
Tip for MSMEs
If the alleged fraud hinges on a clerical mismatch (say, an invoice number typo) attach GST-matched ledgers, bank statements, and supporting documents explaining the discrepancy. Where fraud, wilful misstatement, or suppression cannot be established, the taxpayer may challenge the applicability of Section 74. If the relevant appellate authority, tribunal, or court finds the fraud allegation unproven, Section 75(2) provides for determination of the tax as if the notice had been issued under Section 73. Reclassification and penalty relief are not automatic.
2026 update: Section 74 applies to relevant tax periods up to FY 2023–24. For FY 2024–25 onwards, Section 74A applies, with different timelines for qualifying reduced-penalty payments.
Consequences of skipping payment under Section 74
Ignoring an SCN under Section 74 can expose a business to further tax and recovery proceedings. The consequences depend on the facts, the order passed, and the applicable provisions:
- Penalty hits full throttle: If the demand is confirmed and the reduced-penalty conditions are not met, the penalty under Section 74 can equal 100% of the tax due.
- Interest keeps the meter spinning: Interest on delayed tax payment generally applies at 18% per annum under Section 50(1), where applicable, and is calculated for the relevant period of delay.
- Bank accounts and property: The department may initiate recovery proceedings. Provisional attachment of bank accounts or property is possible only when the statutory conditions under Section 83 are met; it is not automatic merely because an SCN is ignored.
- Your GSTIN is at stake: Registration may be affected if separate grounds and legal requirements for suspension or cancellation are met.
- E-way bills: Restrictions may apply in specified circumstances under GST rules, but ignoring an SCN does not automatically block all e-way bills.
- Big amounts invite criminal scrutiny: Certain offences under Section 132 can attract prosecution. For specified tax-evasion offences, the punishment can extend to five years’ imprisonment where the amount exceeds ₹5 crore, subject to the statutory requirements. Prosecution is not automatic merely because a tax demand is raised.
A story that stings
Last year a Jaipur‑based fabricator ignored a ₹10‑lakh SCN, assuming “it’ll sort itself out.” It didn’t. Six months later the adjudicating order doubled the bill. The tax office froze his company’s main current account the same week payroll was due. Vendors balked, projects stalled, and the business spent the next quarter fighting for working capital instead of chasing orders.
Lesson: pay early, sleep better.
Common defences against a Section 74 Show Cause Notice (SCN)
A fraud-tagged SCN doesn’t automatically make you guilty. Below are the arguments tax advisers may consider when the department’s case is disputed or the evidence is insufficient. Use the ones that fit your facts, and document everything – each defence must be supported by relevant records and applicable law.
| Defence angle | When it may apply | What to show the officer |
|---|---|---|
| Fat-finger errors | Numbers went wrong because someone keyed in “11,00,000” instead of “1,10,000,” or made an error in HSN mapping. | Original invoices, amended returns, corrected ledgers, and a written explanation supported by documentary evidence. |
| Grey-zone interpretation | The Act or CBIC circulars are unclear, and you chose a reasonable interpretation. For example, whether a SaaS export qualifies as an export of services or falls under OIDAR provisions. | Copies of relevant circulars, advance rulings, industry position papers, and your internal tax memo documenting the interpretation adopted. |
| Time-bar defence | The SCN or adjudication order is issued beyond the applicable statutory limitation period. Under Section 74, the order must generally be issued within five years from the due date for furnishing the annual return for the relevant financial year, or from the date of erroneous refund, as applicable. The SCN must be issued at least six months before the order deadline. | Proof of the relevant annual return due date, SCN issue date, date of erroneous refund where applicable, and a timeline showing the statutory deadline. |
| No evidence of intent | The department alleges suppression or fraud but relies mainly on a mismatch without sufficient evidence to establish the required intent to evade tax. | Bank statements, e-way bills matching the books, supplier confirmations, invoices, and reconciliation statements. Challenge the fraud allegation with reference to the applicable statutory provisions. |
| Third-party mismatch | The short-payment allegation arises from a vendor uploading the wrong GSTIN or invoice value. | Vendor’s written confirmation, revised GSTR-1 records where available, purchase invoices, payment evidence, and correspondence showing that you sought correction. |
Real‑life save
A SaaS start-up facing a Section 74 SCN over the classification of export services could submit relevant advance rulings, contracts, invoices, and foreign inward remittance evidence to support its position. However, an advance ruling is binding only in the circumstances prescribed under GST law, and foreign exchange receipts alone do not establish that a transaction qualifies as an export of services. The taxpayer must demonstrate that the applicable legal conditions are satisfied.
If the fraud allegation cannot be sustained, the taxpayer may challenge the applicability of Section 74. Section 75(2) provides for determining the tax as if the notice had been issued under Section 73 when the relevant appellate authority, tribunal, or court concludes that the charges of fraud, wilful misstatement, or suppression of facts are not established. Reclassification and penalty relief are not automatic.
Pro tip: Always reply to the SCN within the 30‑day window, even if your defence is still cooking. A brief, factual letter reserving your right to add evidence buys goodwill—and sometimes an extension.
Section 73 vs Section 74 vs Section 74A: Spot‑the‑difference cheat sheet
The GST Act provides different provisions for determining unpaid tax, depending on the financial year and whether fraud, wilful misstatement, or suppression of facts is involved. Choosing the correct provision matters because the limitation periods, penalties, and voluntary payment windows differ.
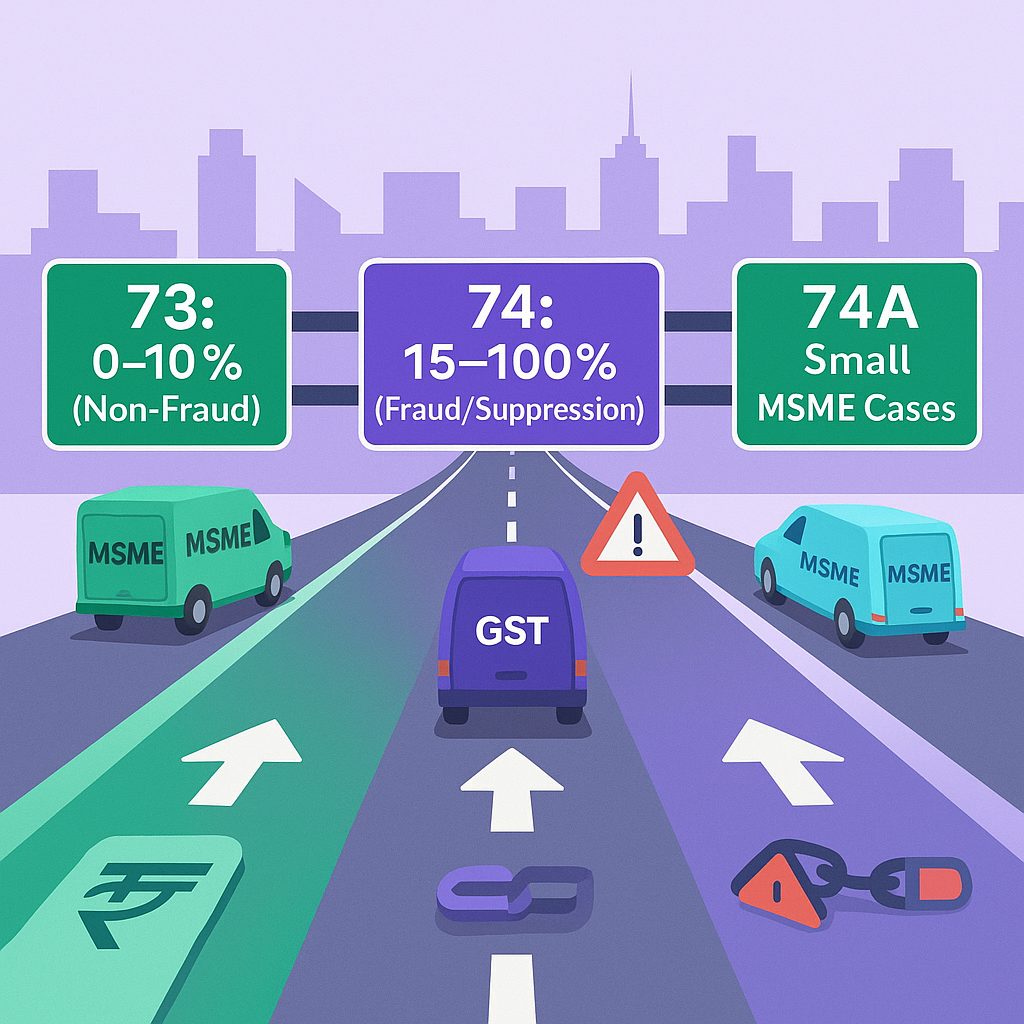
| Feature | Section 73 (Non-fraud) | Section 74 (Fraud/wilful misstatement) | Section 74A (FY 2024–25 onwards) |
|---|---|---|---|
| Applicable period | Up to FY 2023–24 | Up to FY 2023–24 | FY 2024–25 onwards |
| Trigger | Tax short-payment, erroneous refunds, or wrongly availed or utilised ITC for reasons other than fraud or wilful misstatement or suppression to evade tax. | Tax short-payment, erroneous refunds, or wrongly availed or utilised ITC due to fraud, wilful misstatement, or suppression of facts to evade tax. | Covers both fraud and non-fraud cases; the applicable penalty depends on the circumstances. |
| SCN time limit | Generally, within 3 years from the due date of the annual return, or from the date of erroneous refund, as applicable. | Generally, within 5 years from the due date of the annual return, or from the date of erroneous refund, as applicable. | Generally, within 42 months from the due date of the annual return, or from the date of erroneous refund, as applicable. |
| Penalty if paid before SCN | No penalty if tax and applicable interest are paid and the statutory conditions are met. | 15% of the tax | Non-fraud: no penalty. Fraud: 15% of the tax, subject to the applicable conditions. |
| Penalty if paid after SCN | No penalty if tax and interest are paid within 30 days of issue of the SCN. | 25% of the tax if paid within 30 days of issue of the SCN. | Non-fraud: no penalty if tax and interest are paid within 60 days of issue of the SCN. Fraud: 25% of the tax if paid within 60 days. |
| Penalty after adjudication | 10% of the tax or ₹10,000, whichever is higher, subject to the law. | 100% of the tax, unless the reduced-penalty conditions are met. A 50% penalty may apply if payment is made within 30 days of communication of the order. | Non-fraud: 10% of the tax or ₹10,000, whichever is higher. Fraud: 100% of the tax, with a 50% reduced penalty available for qualifying payment within 60 days of communication of the order. |
| Interest | Generally 18% p.a. on delayed tax payments under Section 50(1), where applicable. | Generally 18% p.a. under Section 50(1), where applicable. | Generally 18% p.a. under Section 50(1), where applicable. Different provisions may apply to wrongly availed and utilised ITC. |
| Criminal prosecution | May apply if the facts constitute an offence under Section 132; it is not determined by Section 73 alone. | Possible where the requirements of Section 132 are met. Certain offences involving amounts above ₹5 crore can attract imprisonment of up to five years. | Also possible where the requirements of Section 132 are met; Section 74A does not provide a blanket exemption from prosecution. |
| Best suited to | Genuine errors, ITC discrepancies, and other non-fraud tax demands. | Cases involving alleged fraudulent invoices, concealed sales, or deliberate suppression of taxable transactions. | Tax demands from FY 2024–25 onwards, whether fraud or non-fraud is alleged. |
Heads-up for 2026: Section 74A is already in force for FY 2024–25 onwards; its penalty framework is not awaiting draft rules. For non-fraud cases, the penalty is generally 10% of the tax or ₹10,000, whichever is higher, when an order is passed. For fraud cases, the penalty can equal 100% of the tax, with reduced-penalty options for eligible voluntary payments. Always verify the applicable provision, statutory deadlines, and payment conditions before filing Form GST DRC-03.
Conclusion
Section 74 looks fierce on paper, yet it still hands you the steering wheel. Spot the under-payment, run the maths, and clear the dues before the notice lands or, where eligible, within 30 days of the SCN being issued. Do that and the penalty can be significantly lower, not a hammer. Drag your feet and the penalty can rise to 100% of the tax, interest piles up, and recovery proceedings or other legal consequences may follow, depending on the circumstances.
As of 2026, remember that Section 74 applies to relevant tax periods up to FY 2023–24, while Section 74A governs tax determination from FY 2024–25 onwards. Understanding the applicable provision, voluntary payment deadlines, interest, and penalty rules helps MSMEs make informed GST compliance decisions and reduce the risk of prolonged disputes.
Bottom line? Act while the line‑item is small, and the law stays on your side.
Empowering MSMEs to grow smarter
Tata nexarc delivers powerful solutions for MSMEs—discover tenders, access business loans, grow your online presence, and streamline procurement. Everything your business needs, all in one place.
FAQs
Can I revise or withdraw a DRC-03 after submitting it?
DRC-03 generally cannot be edited or withdrawn directly after submission. If you make an error, contact the jurisdictional GST officer to determine the appropriate correction procedure.
Is voluntary payment under Section 74 allowed if a GST audit or investigation has already started?
Yes. Voluntary payment through DRC-03 may be made during an audit or investigation, subject to applicable provisions. Section 74 covers periods up to FY 2023–24; Section 74A generally applies from FY 2024–25 onwards. Payment timelines and penalty relief depend on the applicable section and stage of proceedings.
What documents should I keep after making a DRC-03 payment?
Keep the filed DRC-03, payment challan, electronic ledger debit details, payment confirmation, and any departmental acknowledgment or order. These records help establish payment and support future audits or enquiries.
Can DRC-03 payments be made using balance in my electronic cash or credit ledger?
Yes, subject to the nature of the liability. The electronic cash ledger can be used to pay tax, interest, and penalties. Eligible tax liabilities may be paid using the electronic credit ledger, subject to restrictions; interest and penalties must be paid in cash.
What if I paid under Section 73 instead of Section 74 by mistake?
Contact your jurisdictional GST officer promptly and explain the error with supporting documents. The correction or adjustment depends on the relevant tax period, the nature of the mistake, and the applicable GST procedure. Do not assume the payment will automatically be reclassified.
Does making a voluntary payment under Section 74 affect my GST compliance rating?
A voluntary DRC-03 payment does not automatically improve or reduce your GST compliance rating. Ensure that the payment is correctly reported and that all other applicable filing and compliance obligations are met.
Can I claim penalty or interest paid under Section 74 as a business expense for income tax?
Penalties incurred for an offence or an expenditure prohibited by law are generally not deductible under the Income-tax Act. The deductibility of GST interest depends on its nature and the applicable income-tax provisions, so seek professional advice before claiming it.
How do I check if my DRC-03 payment has been accepted by the department?
Check your DRC-03 filing status, payment details, and electronic ledger entries on the GST portal. Where applicable, look for a departmental acknowledgment or order. Payment confirmation alone does not mean that the proceedings have been formally closed.
Can I file a DRC-03 for each GSTIN separately if my business has multiple registrations?
Yes. Payments must be reported against the relevant GSTIN and liability. Each GSTIN is treated as a distinct person under GST law, so verify the correct registration before submitting DRC-03.
What if I overpaid tax, interest, or penalty under Section 74—can I get a refund?
A refund may be available if the excess payment qualifies under the applicable GST refund provisions. File Form GST RFD-01 where permitted, provide supporting evidence, and meet the relevant conditions and time limits. A refund is not automatic simply because a DRC-03 payment was higher than required.
A product manager with a writer's heart, Anirban leverages his 6 years of experience to empower MSMEs in the business and technology sectors. His time at Tata nexarc honed his skills in crafting informative content tailored to MSME needs. Whether wielding words for business or developing innovative products for both Tata Nexarc and MSMEs, his passion for clear communication and a deep understanding of their challenges shine through.
every section has some sub section and its sub-section are so confusing. Always have to consult accountant for the same.
You can go through the link given on the article which has screenshot based guidance on the same. That will not create more confusion to you.